Buy Before You Sell: Why Mortgage Brokers Should Identify the Scenario Early
Published on Jul 23, 2026
A borrower does not have to wait until their current home sells before exploring the purchase of their next one. For mortgage brokers working with homeowners who have available equity, identifying a Buy Before You Sell scenario early can provide more options when the right property becomes available.
A recent Consumer Bridge Loan scenario brought to Harbor Lending shows why timing matters.
The borrower found the neighborhood they wanted
A mortgage broker was working with a borrower who wanted to move into a particular neighborhood.
Then a highly sought-after home became available.
The borrower wanted the property, but they still owned their current residence. At that point, the purchase structure available to them depended on the sale of their existing home.
In other words, their offer needed a sale contingency.
The mortgage broker recognized the problem and contacted Harbor Lending to see whether a Consumer Bridge Loan could provide another option.
The goal was to remove the sale contingency
Harbor Lending’s Consumer Bridge Loan is designed for qualified homeowners who want to Buy Before You Sell.
The structure can use available equity in the departing property to help finance the next purchase. One loan is secured by the purchase property and the departing property.
For the right scenario, that can allow the borrower to purchase before selling their current home and make an offer without a sales contingency.
That was exactly what this mortgage broker was trying to accomplish.
But there was another factor working against the borrower: time.
The financing solution was identified too late in the process
By the time Harbor became involved, the borrower was already competing for the property.
There was not enough time to get the new financing structure in place before the seller made a decision.
The seller ultimately accepted another buyer’s offer.
Harbor did not close the loan.
And that is what makes this scenario worth discussing.
What happened to the borrower?
The borrower’s desire to live in the neighborhood did not change.
Instead of purchasing the original home, they bought a lot very close to it and decided to build.
They can now continue living in their existing home while their new property is constructed.
It turned into a different solution for the borrower.
But the original transaction highlighted something mortgage brokers should think about well before an offer is written.
The Buy Before You Sell conversation should happen early
The time to identify a potential Buy Before You Sell scenario is before the borrower writes the offer.
The opportunity can often be identified much earlier.
Consider the borrower who says:
“We want to move, but we need to sell this house before we can buy the next one.”
That statement should trigger another conversation.
- Does the borrower have available equity in the current property?
- What are they trying to accomplish?
- What does the purchase look like?
- What is the exit strategy for the short-term financing?
Those are the kinds of questions that can help identify whether a Consumer Bridge Loan is worth evaluating before the borrower ever writes an offer.
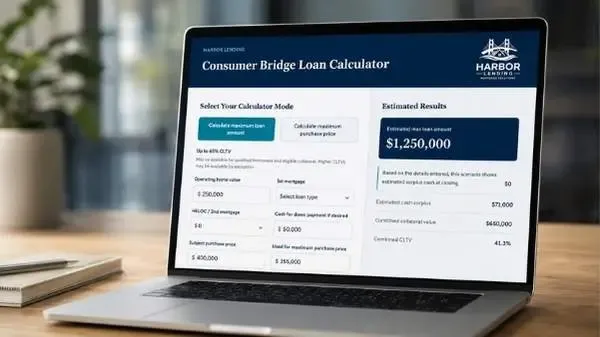
Mortgage brokers can also use Harbor’s Consumer Bridge Loan Calculator to evaluate the borrower’s equity position and estimate a potential loan structure before submitting the scenario for review.
Harbor’s broker guidance follows the same approach. Start with the borrower’s equity position, the story and what they are trying to accomplish, and the exit strategy. Harbor can evaluate the structure from there.
A Buy Before You Sell scenario may be worth evaluating when:
- The borrower has meaningful equity in the current home.
- 100% or more purchase financing may be possible based on available equity.
- The departing home and next purchase are in different states.
- The borrower wants to make an offer without a sales contingency.
Preparation can change the broker’s conversation
Knowing the structure ahead of time does not guarantee that a borrower will win a property.
What it does is give the mortgage broker another potential option to discuss with the borrower and their real estate agent.
Instead of discovering after the fact that a sale contingency created an obstacle, the parties may be able to evaluate a Buy Before You Sell structure while they are planning the purchase.
That preparation can give the borrower greater clarity about what they may be able to do when the right property appears.
It also gives the mortgage broker another way to demonstrate value beyond the long-term financing.
The lesson from a loan we didn’t close
This was not a Harbor Lending closing story.
It was a timing story.
The broker recognized that a Consumer Bridge Loan might provide a way for the borrower to make an offer without a sales contingency, but the opportunity was already moving too quickly.
For mortgage brokers, the takeaway is simple:
Do not wait until a sale-contingent offer is already in play to start thinking about Buy Before You Sell financing.
When a borrower has available equity and plans to purchase before their current home is sold, start the conversation early.
Because sometimes the most valuable financing option is the one you understand before you need it.
Have a Buy Before You Sell scenario?
Learn more about Harbor’s Consumer Bridge Loan here
Run a scenario with the Consumer Bridge Loan Calculator
Subject to approval and program guidelines. Not all borrowers or properties will qualify. Program availability may vary by state. This is not a commitment to lend.
Email: Sales@harborlending.com
Phone: 833-734-1038
Website: harborlending.com
Consumer Bridge Loan: AZ, CA, CO, FL, ID, MN, NV, NJ, OH, OR, PA, TN, and WA.
Consumer Bridge Loan coming soon: GA and UT.
Business Purpose Loan and 1031 Exchange Loan: Available nationwide except AK, ND, NY, TX, UT, and, VT.
Your Safe Harbor for Mortgage Lending
Nextres, LLC dba Harbor Lending dba Harbor Home Lending (AZ, CA). NMLS ID: 2321794. Licensed in AZ, CA, CO, FL, ID, MN, NV, NJ, OH, OR, PA, TN, WA. California Department of Financial Protection and Innovation: 60DBO-165440. Loans will be arranged or made pursuant to a California Department of Financial Protection and Innovation license.
Loans are subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not constitute an approval for financing or an interest rate guarantee. Program availability may vary by state. This is not a commitment to lend. Not all borrowers or properties will qualify. Equal Housing Opportunity.